Apple Faces Sales Downgrade Ahead of iPhone Duo Launch
Investment firm Loop Capital has downgraded its rating for Apple stock from “Buy” to “Hold” as anticipation builds for the upcoming iPhone Duo release. This shift in market sentiment stems from concerns that the anticipated recovery in iPhone sales volume will not materialize as previously projected. Analysts now believe that the approximately 13 million units cut from production plans in late 2026 will not be recovered, challenging earlier assumptions that supply chain constraints would be temporary. This revision has directly impacted the company’s valuation, with the target stock price being lowered from $370 to $330, signaling a more cautious outlook for the tech giant’s immediate financial trajectory.
- Loop Capital downgraded Apple stock to “Hold” due to weakening sales recovery projections.
- Apple is not expected to recover 13 million units removed from its 2026 production schedule.
- Market analysts lowered the target price for Apple shares from $370 to $330.
- The company’s December quarter shipment forecast of 79 million units falls short of the 85 million unit market consensus.
December Quarter Projections are Falling Short
The financial outlook for the final quarter of the year has faced downward revisions as market analysts adjust their expectations. While Apple management remains optimistic, the broader market anticipates shipments of 85 million units, whereas current data suggests a more conservative figure of 79 million iPhones. Furthermore, the average selling price (ASP) forecast has been reduced from $1,239 to $1,123, reflecting a potential shift in consumer preference or product mix. This downward adjustment highlights the challenges the company faces in maintaining its premium pricing strategy amidst a tightening economic environment.
Long Term Revenue Streams are Facing Pressure
Projections for 2027 present a complex picture for Apple’s financial health. Although the total number of iPhones sold is expected to reach 260 million—surpassing previous estimates—the revenue generated per device is anticipated to decline significantly. The projected average selling price has been lowered from $1,235 to $1,096, which subsequently brings the total revenue forecast down from $315 billion to $285 billion. Industry experts also warn that rising memory component costs are likely to exert significant pressure on Apple’s profit margins in the coming years.
Product Launch Schedules are Complicating Market Analysis
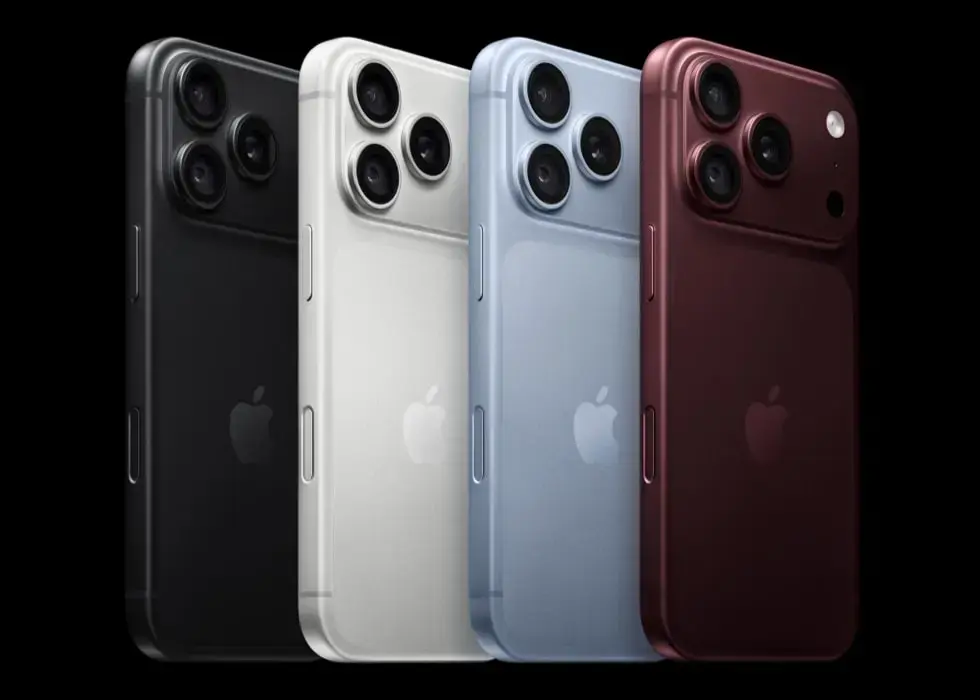
The strategic decision to stagger product releases has made interpreting Apple’s recent financial performance more difficult for investors. While the iPhone 18 Pro models debuted in September, the iPhone Duo is scheduled for an October 23 release, with standard and budget-friendly models expected to arrive in the spring of 2027. The absence of a standard model launch this autumn is cited as a primary factor contributing to the decline in third-quarter shipment volumes. Despite these headwinds, Apple continues to demonstrate resilience in a challenging market. While global smartphone shipments plummeted by 20 percent year-over-year in the third quarter due to memory shortages, Apple successfully increased its market share from 18 percent to 22 percent, marking its strongest third-quarter performance to date. The industry is now closely watching whether the high-priced iPhone Duo can effectively bridge the current revenue gap.
How do you view these latest market projections for Apple? Do you believe the launch of the iPhone Duo will be enough to offset the current supply chain and pricing challenges, or is the market right to be cautious? Share your thoughts in the comments below.
Your comment has been submitted,
it will be published after approval.