Trendyol and Hepsiburada Command Over 40% of Turkey’s Cargo
E-commerce giants Trendyol and Hepsiburada have collectively shouldered a substantial 40.77% of Turkey’s total cargo volume during the first half of 2026, according to the latest market data report from the Information Technologies and Communications Authority (BTK). This significant share, highlighted in the “2026 First Half Turkey Postal Sector Market Data Report,” underscores the profound transformation within the logistics sector, with online retail platforms increasingly dominating the movement of goods across the nation. The report reveals a total of 728.31 million cargo and parcel shipments nationwide, generating 87.90 billion TL in revenue over this six-month period, clearly illustrating the expanding influence of e-commerce in the country’s cargo market share.
- E-commerce platforms Trendyol and Hepsiburada together accounted for 40.77% of Turkey’s total cargo volume during the first half of 2026.
- The “2026 First Half Turkey Postal Sector Market Data Report” by the Information Technologies and Communications Authority (BTK) revealed a total of 728.31 million cargo and parcel shipments, generating 87.90 billion TL in revenue.
- Corporate shipments constituted 96.24% of all deliveries, indicating a significant reliance on digital platforms for logistics operations.
- Despite leading in package volume, Trendyol captured only 21.11% of the total cargo revenue, while traditional carriers like Yurtiçi Kargo achieved a higher revenue share (17.34%) with significantly fewer packages.
E-commerce Logistics Networks Now Dominate the Market
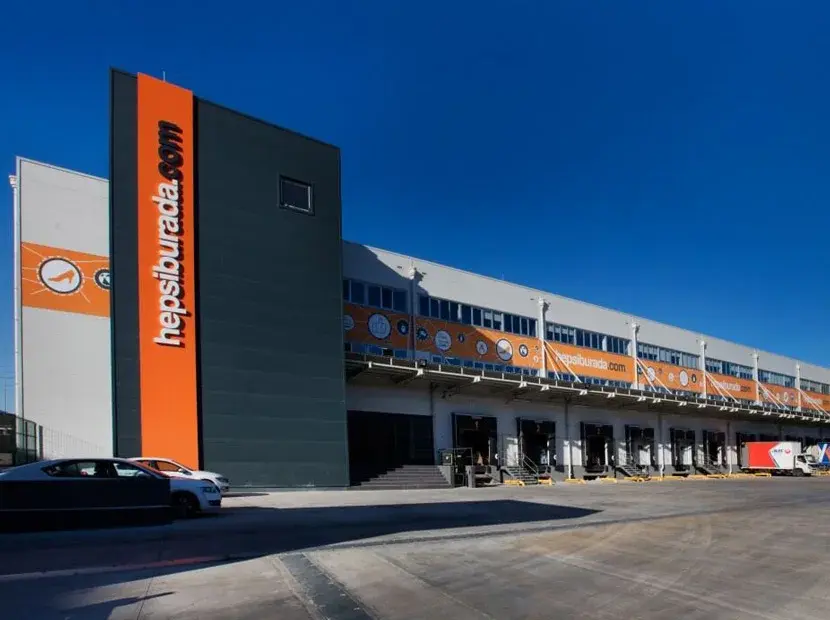
The first six months of 2026 unequivocally demonstrate the evolution from traditional transportation to digital retail. The data indicates that an overwhelming 96.24% of all cargo shipments originated from corporate entities, signifying a clear decline in individual shipments and a growing dependency of the sector on the logistics networks of digital platforms. In terms of volume, Trendyol alone has emerged as the market leader, claiming a 30.89% share. Hepsiburada’s logistics arm, HepsiJet, contributes an additional 9.88%, bringing the combined share of these two e-commerce powerhouses to an impressive 40.77% of the total market.
Traditional cargo companies find themselves trailing in this new landscape. Aras Kargo holds an 11.62% share, followed closely by Yurtiçi Kargo at 11.07%, and MNG Kargo with 10.14%. These figures position them behind the extensive logistics networks established by the e-commerce giants. Online retail platforms have particularly accelerated in micro-package transportation, focusing on lightweight products such as cosmetics, textiles, and small electronic items, which can be efficiently transported in large quantities by a single delivery vehicle.
Strategic Differences Emerge Between Volume and Revenue
An intriguing pattern emerges when comparing the number of packages transported with the revenues generated from these deliveries. Trendyol, despite handling approximately one-third of the total cargo volume, managed to secure only 21.11% of the sector’s total cargo revenues. This discrepancy suggests a focus on high-volume, potentially lower-margin shipments for the e-commerce leader.
Conversely, Yurtiçi Kargo, which transported 80.6 million packages—roughly one-third of Trendyol’s operational volume—achieved a 17.34% share of the total revenue. This indicates that traditional cargo companies like Yurtiçi Kargo are likely concentrating on higher-value consignments or employing different pricing models, enabling them to surpass e-commerce logistics firms in terms of profitability per package.  This strategic divergence highlights that traditional carriers might be handling more specialized or premium services.
Another facet of e-commerce giants’ logistics strategy is evident in the physical weight of the products they transport. Heavy, bulky items exceeding 30 kilograms, or those requiring warehouse transportation such as white goods and furniture—products that often necessitate two personnel for handling—are typically directed towards traditional cargo networks or specialized logistics firms. This strategic separation underscores that the logistics sector is currently evolving along two distinct paths, each catering to different types of shipments and operational models.
The rapid expansion of e-commerce logistics networks is undeniably reshaping the industry. How do you believe this rapid growth will impact the future of traditional cargo companies in Turkey? Share your thoughts in the comments below!
Your comment has been submitted,
it will be published after approval.